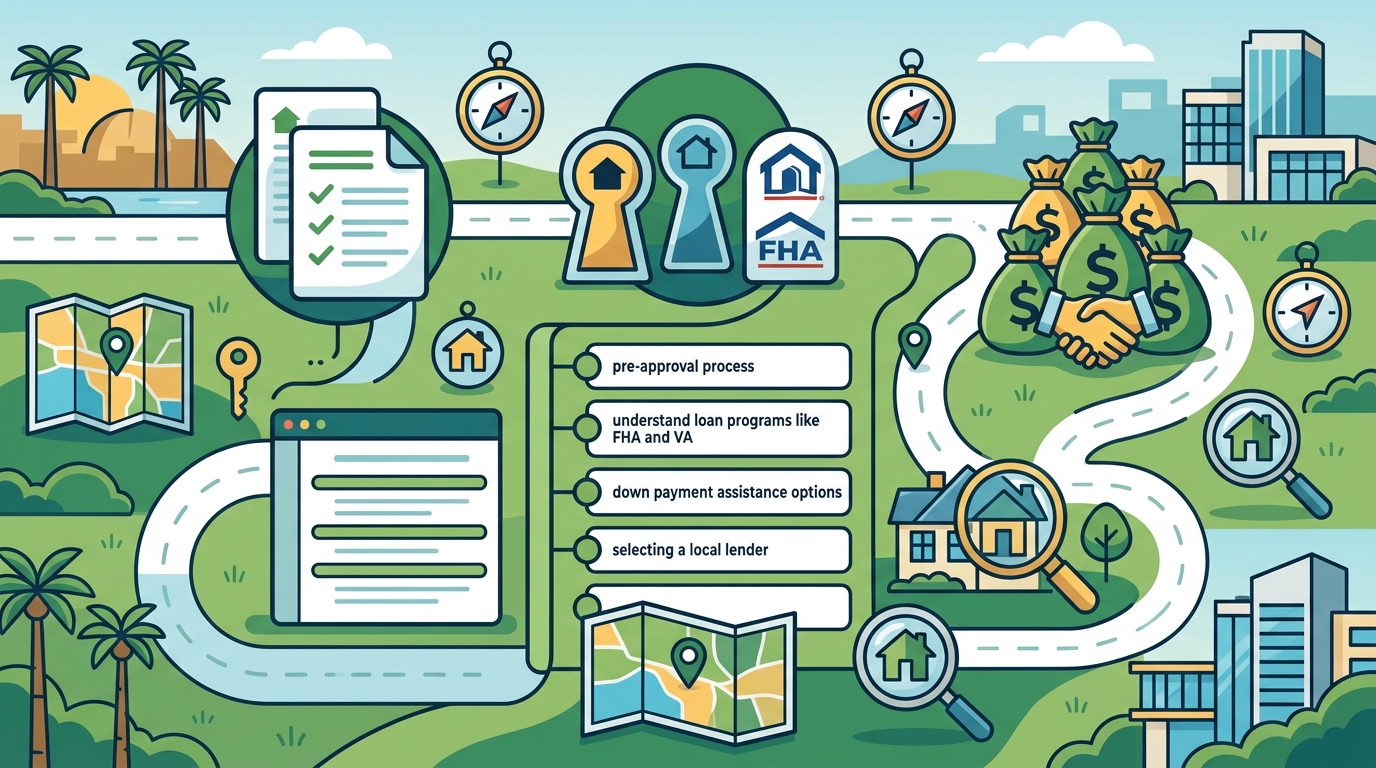
For buyers in Tempe, Arizona, Tukuandco provides direct access to financing guidance by connecting clients with experienced local mortgage professionals. This guide covers the essential steps for securing a mortgage, including how to select a local lender, understand loan programs like FHA and VA, and navigate the pre-approval process. We will also explore down payment assistance options available in the Valley to help you buy your home with confidence.
Local Mortgage Lenders in the Valley
Choosing the right lender is the first critical step in your home buying journey. A local mortgage lender is a financial institution that operates within your specific geographic region, offering personalized service and a deep understanding of local real estate trends. In the Phoenix and Tempe areas, working with a lender who understands the nuances of the local market can significantly streamline your closing process.
Why Local Expertise Matters
Local lenders often have established relationships with local title companies, real estate agents, and appraisers. This network can help prevent delays that might occur with large national banks that process loans through distant call centers. When you work with Tukuandco's financing partners, you gain access to a Senior Mortgage Loan Officer who has dedicated nearly 33 years to helping people secure mortgages in the community.
Types of Lenders to Consider
Buyers in Tempe typically choose between three types of lenders: banks and credit unions, mortgage brokers, and direct lenders. Banks and credit unions often offer competitive rates for existing customers, while mortgage brokers can shop your loan around to multiple lenders to find the best terms. Direct lenders, such as those affiliated with local real estate teams, provide a more streamlined experience with direct communication from application to closing.
Understanding Loan Programs: FHA, Conventional, and VA
A loan program is a specific set of guidelines and requirements established by a lender or government agency to finance a home purchase. The three most common programs for buyers in Tempe are FHA, Conventional, and VA loans. Each program has distinct eligibility criteria, down payment requirements, and insurance costs that will impact your monthly payment.
FHA Loans
Federal Housing Administration (FHA) loans are government-backed loans designed to help first-time buyers and those with lower credit scores. These loans typically require a minimum down payment of 3.5% and have more flexible credit requirements than conventional loans. However, they require mortgage insurance premiums (MIP) for the life of the loan if your down payment is less than 10%.
Conventional Loans
A conventional loan is a mortgage that is not insured by a government agency. These loans are often the best option for buyers with strong credit scores (700 or higher) and the ability to make a larger down payment. Conventional loans may require private mortgage insurance (PMI) if your down payment is less than 20%, but this insurance can be removed once you reach 20% equity in your home.
VA Loans
Department of Veterans Affairs (VA) loans are available to eligible veterans, active-duty service members, and certain spouses. The primary advantage of a VA loan is that it often requires zero down payment and does not require mortgage insurance. This makes it an incredibly powerful tool for military families looking to buy in Tempe or the wider Phoenix metro area.
| Loan Type | Minimum Down Payment | Minimum Credit Score | Mortgage Insurance |
|---|---|---|---|
| FHA | 3.5% | 580 | Required (MIP) |
| Conventional | 3% - 20% | 620 - 700 | PMI if < 20% down |
| VA | 0% | 580 - 620 | Not Required |
Down Payment Assistance Programs
Down payment assistance (DPA) is a financial resource that helps homebuyers cover the upfront costs of purchasing a home. These programs can take the form of grants, low-interest loans, or deferred loans that do not need to be repaid immediately. For buyers in Tempe and the Phoenix metro area, several state and local programs are available to reduce the barrier to entry for homeownership.
State and Local Options
Arizona offers various DPA programs through the Arizona Housing Finance Authority (AHFA) and local community action agencies. These programs often target first-time homebuyers, low-to-moderate income households, and those purchasing in designated affordable housing areas. It is important to check eligibility requirements early in your search, as some programs require you to complete homebuyer education courses.
How DPA Works with Your Loan
Down payment assistance can often be stacked with certain loan programs, such as FHA or Conventional loans. For example, you might use a DPA grant to cover your 3.5% FHA down payment and closing costs. Working with a knowledgeable agent from Tukuandco ensures that you are aware of all available incentives that can lower your out-of-pocket expenses.
The Pre-Approval Process Explained
Mortgage pre-approval is a formal evaluation of your financial situation by a lender, resulting in a letter that confirms how much you are qualified to borrow. This is different from pre-qualification, which is a preliminary estimate based on self-reported information. A pre-approval letter is a powerful tool in a competitive market like Tempe, as it shows sellers that you are a serious and financially vetted buyer.
Steps to Get Pre-Approved
The pre-approval process typically involves four main steps. First, you gather your financial documents, including pay stubs, tax returns, and bank statements. Second, you submit a loan application to your chosen lender. Third, the lender orders a credit report and verifies your income and assets. Finally, the lender issues a pre-approval letter stating your maximum loan amount and estimated interest rate.
Why Pre-Approval is Critical in Tempe
In the Phoenix metro area, homes often receive multiple offers within days of hitting the market. Sellers are more likely to accept an offer from a pre-approved buyer because it reduces the risk of the deal falling through due to financing issues. By securing pre-approval before you start your house hunt, you can make faster, more confident offers and negotiate from a position of strength.
Key Takeaways
- Local lenders in the Valley often provide faster service and better local market knowledge than large national banks.
- FHA loans are ideal for first-time buyers with lower credit scores, requiring only 3.5% down.
- VA loans offer zero down payment and no mortgage insurance for eligible military members and veterans.
- Conventional loans are best for buyers with strong credit and the ability to put down 20% to avoid PMI.
- Down payment assistance programs in Arizona can significantly reduce your upfront costs.
- Pre-approval is a formal financial vetting process that makes you a more competitive buyer in the Tempe market.
- Working with a real estate agent who has a trusted mortgage partner, like Tukuandco, simplifies the entire financing journey.
Frequently Asked Questions
What is the difference between pre-qualification and pre-approval?
Pre-qualification is a quick, informal estimate of how much you might borrow based on information you provide. Pre-approval is a formal process where the lender verifies your income, assets, and credit, resulting in a letter that confirms your borrowing power.
How much do I need for a down payment in Tempe?
The minimum down payment varies by loan type. FHA loans require 3.5%, conventional loans can start as low as 3%, and VA loans require 0%. Many buyers in Tempe aim for 20% to avoid mortgage insurance, but lower down payments are possible with the right loan program.
Can I use down payment assistance with an FHA loan?
Yes, many down payment assistance programs in Arizona can be used in conjunction with FHA loans. This allows you to use the assistance funds to cover your 3.5% down payment and closing costs.
How long does the pre-approval process take?
The pre-approval process typically takes 2 to 5 business days, depending on how quickly you can provide your financial documents and how busy the lender is. Having your documents organized in advance can speed up the process significantly.
Do I need a high credit score to get a VA loan?
While there is no official minimum credit score set by the VA, most lenders require a score of at least 580 to offer a zero-down payment VA loan. Some lenders may approve borrowers with scores as low as 500, but they may require a down payment.
Who can I contact for financing guidance in Tempe?
You can reach out to Tukuandco to connect with their trusted mortgage partners. They can help you navigate the options and find the right lender for your specific financial situation.
Conclusion
Navigating the home buying process in Tempe, Arizona, requires a solid understanding of your financing options. By choosing a local lender, selecting the right loan program, and exploring down payment assistance, you can make your dream of homeownership a reality. Tukuandco is committed to helping you every step of the way, from your first consultation to the day you get your keys. Contact us today to start your journey to a new home in the Valley.